October 31, 2026
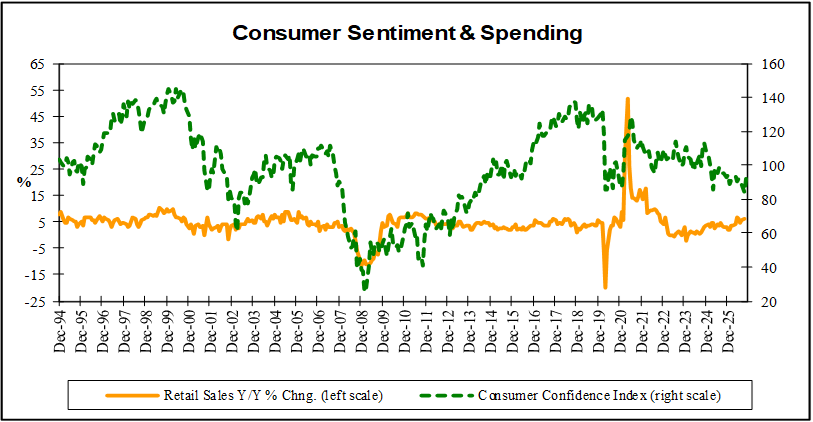
Coming into the October 27-28 Federal Open Market Committee (FOMC) meeting, the central bank faced an ambiguous outlook. Consumer spending ended the quarter strong even as sentiment is weak; unemployment is at a historically low level, but wage growth has slowed; price pressures have accelerated, but business activity has also grown, putting the economy on decent footing. The AI boom could also lead to a productivity surge or spur job cuts. The Fed is also faced with the age-old dilemma of raising rates too quickly and risking harm to vulnerable businesses and households or moving too slowly and falling further behind the curve on inflation because their policy moves take time to feed through to the economy.
As widely expected, the Fed decided not to change the targeted federal funds range after lifting it by 25 basis points at the September meeting. The decision had dissenters as two Committee members favored hiking rates. There is little doubt that the Committee remains broadly aligned in viewing inflation as the primary policy challenge and the absence of a rate hike should not be mistaken for the end of a tightening cycle. The bottom line is the Fed still has work to do.
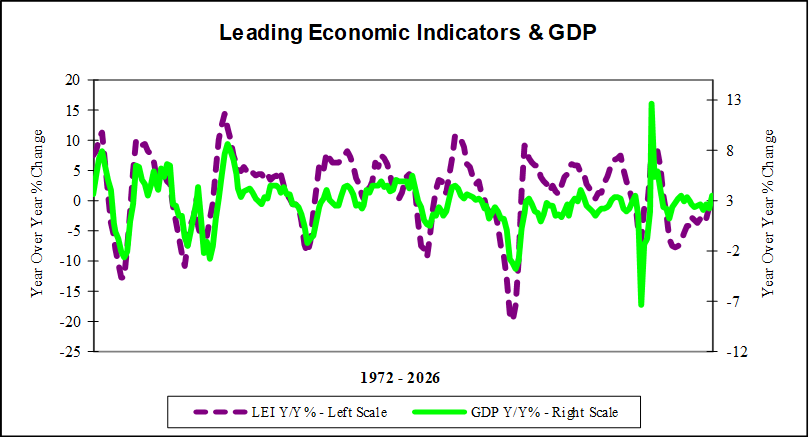
U.S. business activity grew at a better pace in the third quarter. The first estimate for GDP for the 3rd quarter was 3.4%, stronger than anticipated. It was boosted by strong consumer spending, AI-fueled investment and related build-out, along with outlays to defense companies. The Institute for Supply Management (ISM) Purchasing Managers' Index (PMI) for both manufacturing and non-manufacturing remain comfortably in expansion territory. Yet there are also strains within the economy. Small business confidence broadly deteriorated in September as most firms surveyed reported slower earning trends and softer expectations for the economy moving forward. Most notable is the interest-rate-sensitive housing sector. Single-family building permits and the National Association of Home Builders (NAHB) Housing Market Index have fallen to multi-year lows.
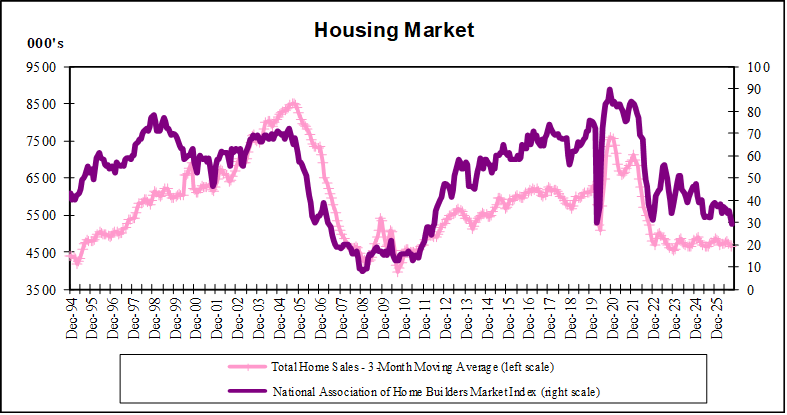
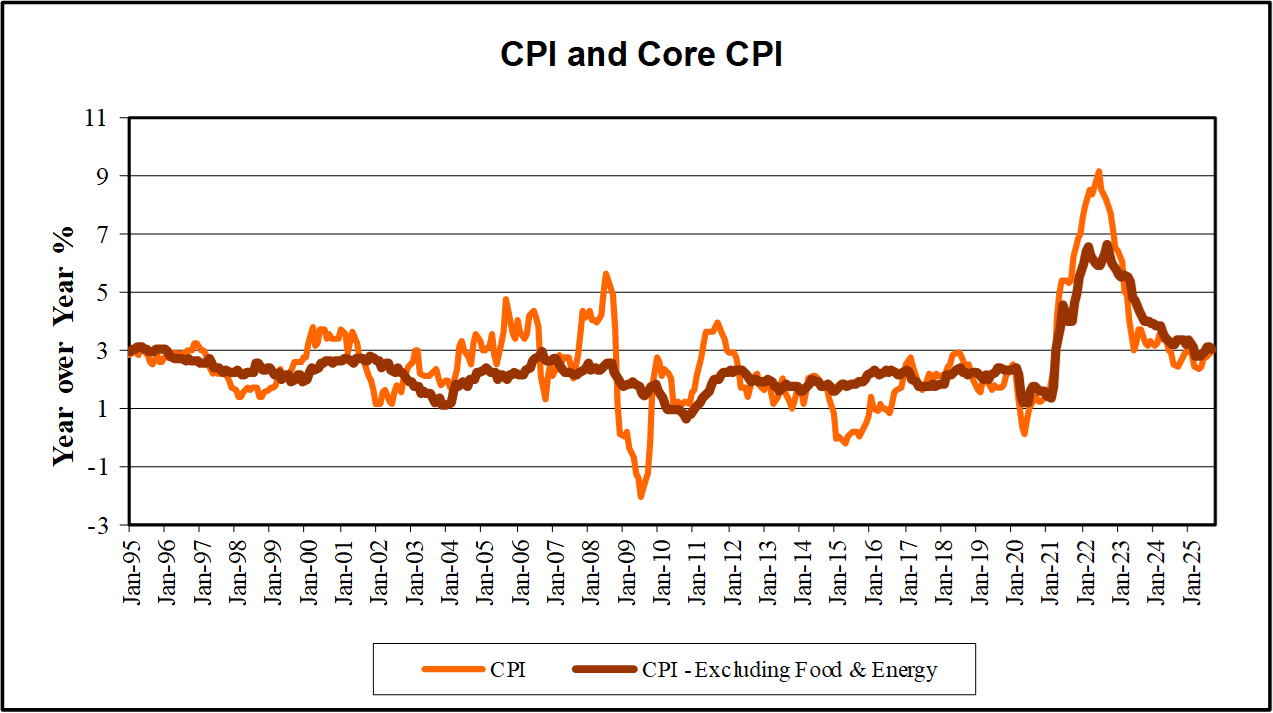
Under more normal conditions, the Fed might respond to housing weakness with easier monetary policy to spur demand by lowering borrowing rates. But with signals that the labor market is stable and the unemployment rate is at a historically low level, the Fed is concentrating on putting the inflation genie back in the bottle. Inflation appears to have gained steam based on recent indicators. Price pressures were relatively broad-based, with firmer readings on commodities (including energy), shelters, core goods and several non-housing services. Increasing price pressures were a common theme in the Federal Reserve’s Beige Book, released two weeks before the FOMC meeting. Some of the Fed’s business contacts expect those pressures to intensify. The Book also hinted to a headwind for consumers, as it reported more caution about spending and an increased sensitivity to rising prices.
Midterm elections, tighter financial conditions, increased market volatility, and signs of strain in interest-rate-sensitive sectors such as housing and credit card delinquencies may have been factors in the Fed’s pause on rates. The Committee wants to see further data and hear from their five appointed task forces to provide critical guidance on the path of interest rates. Barring a stock meltdown or a break-out of world-wide peace, additional rate hikes are likely. Fed Chairman Kevin Warsh, in his post-meeting press conference, once again reiterated and emphasized that the Fed “will deliver price stability.”

 Full Fusion